Collateralised lies and the global illusion of bank bad loans — by Ayinde Ayinde
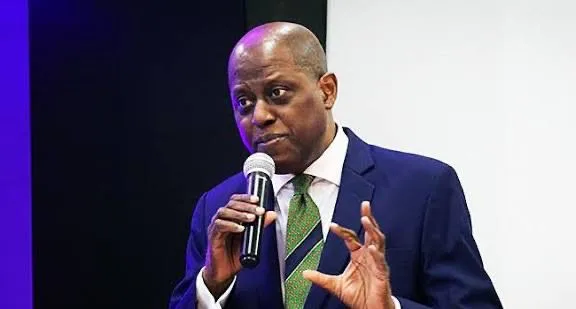
The global banking industry has mastered the dangerous art of appearing sophisticated while quietly normalizing financial contradictions that would collapse under honest scrutiny. Every day, banks announce rising non performing loans as though society should merely accept them as unfortunate economic weather. Yet these same institutions claim that before any major facility is approved, borrowers must provide landed assets, guarantees, legal documentation, insurance cover, cash flow analysis, board resolutions, and heavily scrutinized collateral. The contradiction is terrifying. If these procedures truly exist and function effectively, then the recurring spectacle of catastrophic bad loans should be rare rather than systemic. Somewhere beneath the polished language of banking lies institutional hypocrisy demanding exposure.
Banks portray themselves as guardians of prudence, discipline, and fiduciary responsibility, yet many of the largest bad loans in history did not emerge from poor villagers or struggling petty traders. They originated from elite boardrooms, politically connected conglomerates, and privileged borrowers whose influence opened doors that ordinary citizens could never approach. The tragedy is not merely that loans fail. The tragedy is that many failures were foreseeable from inception. Risk officers often know the weaknesses. Compliance units sometimes detect abnormalities. Internal auditors occasionally identify red flags. Yet transactions proceed because invisible pressures overpower professional ethics. When powerful interests enter the lending room, prudence frequently exits silently through the back door.
The ordinary depositor believes banks operate like scientific institutions driven by objective calculations and measurable safeguards. Unfortunately, reality often resembles political theater disguised in financial language. Many collateral documents celebrated during loan approval become almost useless during recovery because they were inflated, manipulated, duplicated, legally defective, or impossible to liquidate rapidly. Some assets exist only on paper valuations disconnected entirely from market realities. A property valued at billions during credit assessment suddenly becomes unsellable during enforcement. This raises a devastating question. Were those valuations genuinely professional assessments or carefully engineered instruments created to justify predetermined approvals designed to favor influential borrowers behind closed institutional corridors?
The Central Bank exists fundamentally to preserve confidence within the financial architecture of a nation. Yet confidence cannot survive where citizens repeatedly observe massive loan defaults involving politically exposed individuals while small borrowers face relentless intimidation for minor repayment delays. A market woman owing insignificant sums may lose her peace instantly through aggressive recovery measures, but billionaires with strategic connections negotiate endlessly behind protected institutional curtains. Such unequal treatment weakens public faith in banking justice. It creates the perception that financial systems punish weakness while rewarding influence. Once society begins believing that accountability depends on social status rather than ethical principles, institutional credibility starts decaying from within regardless of regulatory declarations or public reassurances.
One of the greatest misconceptions surrounding bad loans is the assumption that all defaults emerge naturally from unfortunate economic conditions. Certainly, economic crises destroy businesses legitimately. Currency devaluation, inflationary shocks, insecurity, policy instability, and global recessions can cripple repayment capacity even among disciplined entrepreneurs. However, not every toxic loan belongs inside this category. Some loans are born unhealthy from their first day of disbursement. They were never structured according to commercial logic. They existed because someone powerful demanded approval, someone influential expected favors, or someone inside the institution anticipated hidden benefits. In such situations, the language of “credit risk” becomes camouflage covering institutional recklessness and concealed ethical compromise within elite banking structures.
The culture of secrecy surrounding large delinquent loans has become one of the most dangerous cancers within modern banking. Banks often refuse transparent disclosure under the excuse of confidentiality, reputational concerns, or ongoing negotiations. Yet ordinary citizens whose deposits sustain these institutions deserve to know how public trust is being endangered. Financial opacity creates fertile ground for abuse because hidden information protects negligent executives and influential debtors from accountability. Transparency does not destroy banking systems. Corruption destroys banking systems. Where secrecy dominates credit administration, manipulation flourishes comfortably. Institutions claiming integrity should welcome scrutiny rather than fear it. Public confidence grows stronger when accountability is visible, measurable, and uncompromising regardless of borrower status or institutional prestige.
Another disturbing reality is insider lending disguised under complex corporate arrangements. Directors, executives, or politically exposed associates sometimes access enormous facilities through proxies, affiliated companies, or layered ownership structures designed to obscure direct relationships. Officially, the loan belongs to an independent corporation. Unofficially, the true beneficiaries sit within the same ecosystem responsible for approval. Such arrangements poison governance because objective risk evaluation becomes impossible when personal interests contaminate professional judgment. The institution gradually transforms from a financial intermediary into a private extraction mechanism benefiting connected elites. Depositors unknowingly finance dangerous concentrations of risk while regulators struggle to penetrate sophisticated webs of influence carefully engineered to appear legitimate within official documentation and compliance procedures.
The phrase “fully secured loan” has become one of the most abused expressions in contemporary banking vocabulary. A loan may appear secured on paper yet remain practically unrecoverable in reality. Collateral perfection requires far more than collecting title documents and signatures. It demands enforceability, liquidity, market relevance, legal clarity, insurance protection, and realistic valuation under distressed conditions. Many institutions deliberately ignore these complexities during aggressive lending cycles because immediate profit targets overshadow long term sustainability. Executives celebrate rapid credit expansion while risks accumulate quietly beneath attractive balance sheets. By the time defaults emerge, responsible officers may have retired, resigned, or transferred elsewhere, leaving institutions and societies to absorb consequences generated through years of concealed imprudence and weak governance.
Judicial inefficiency also contributes heavily to the persistence of bad loans, especially within developing economies. Banks may possess legitimate collateral rights yet remain trapped for years inside endless litigation. Borrowers exploit procedural loopholes, conflicting claims, political influence, and delayed court processes to frustrate recovery efforts indefinitely. During prolonged disputes, assets depreciate, businesses collapse, records disappear, and economic conditions deteriorate further. Thus, even genuine collateral becomes economically weakened by systemic legal paralysis. A nation cannot build a healthy financial system where recovery mechanisms function slower than financial deterioration itself. Justice delayed in credit enforcement becomes economic sabotage because uncertainty discourages responsible lending while emboldening strategic defaulters who understand how institutional weakness can be manipulated against creditors.
Many banks have also become victims of their own greed. The pursuit of aggressive profitability often encourages reckless concentration of exposure within politically glamorous sectors or among highly connected corporate giants. Instead of diversifying responsibly, institutions chase oversized transactions promising extraordinary returns and prestigious relationships. Smaller productive enterprises capable of steady repayment receive limited support while enormous speculative deals dominate lending portfolios. When such concentrated exposures collapse, the resulting damage threatens institutional stability itself. History repeatedly demonstrates that banking crises seldom originate from disciplined small borrowers. They emerge from oversized risks celebrated enthusiastically during boom periods but condemned publicly only after devastating consequences become impossible to conceal from regulators, shareholders, and frightened depositors.
The tragedy of bad loans extends beyond balance sheets into the social fabric of nations. When banks accumulate toxic assets, lending to productive sectors contracts sharply. Entrepreneurs struggle for financing. Manufacturers reduce operations. Employment opportunities decline. Economic growth slows painfully. Entire societies pay the price for institutional irresponsibility committed by a privileged few. The consequences therefore transcend technical banking discussions. Bad loans can deepen poverty, increase inequality, and weaken national development trajectories. Citizens deprived of access to affordable credit because institutions are recovering from reckless elite exposures eventually lose faith not only in banks but also in the fairness of the broader economic system governing their collective future and aspirations.
Another uncomfortable truth rarely discussed publicly is the relationship between political power and banking vulnerability. In many economies, influential politicians maintain direct or indirect relationships with major borrowers, regulators, or banking executives. Such networks create environments where commercial decisions become vulnerable to political calculations. Credit committees may feel pressured to accommodate strategic interests rather than objective risk analysis. Regulators may hesitate to act decisively against institutions connected to powerful figures. Consequently, dangerous loans survive longer than they should while problems compound silently. Financial discipline cannot flourish where political interference overrides professional independence. A banking system captured by elite influence eventually transforms from an engine of development into an instrument for privileged wealth extraction and institutional distortion.
Banks frequently defend themselves by emphasizing that lending inherently involves uncertainty. This is true. No financial system can eliminate risk completely. However, uncertainty should never become an excuse for negligence, manipulation, or deliberate recklessness. Professional banking exists precisely to measure, manage, and price risk intelligently. If institutions continuously approve catastrophic facilities despite possessing armies of analysts, valuers, lawyers, economists, auditors, and compliance professionals, society has every right to question whether incompetence or compromise lies beneath recurring failures. Genuine mistakes occur occasionally. Persistent patterns of disastrous lending suggest deeper systemic sickness. At some point, repeated failures cease being accidents and begin resembling institutionalized irresponsibility protected by technical language and regulatory complexity incomprehensible to ordinary citizens.
Credit committees are supposed to represent the final fortress protecting depositors’ funds from imprudent exposure. Yet history demonstrates that committees sometimes become ceremonial structures approving decisions effectively predetermined elsewhere. Members may fear challenging influential executives or politically sensitive transactions. Dissenting professionals risk marginalization, stalled careers, or forced exits. Over time, institutional cultures evolve where compliance means silence rather than ethical courage. Dangerous consensus replaces independent scrutiny. Once internal resistance collapses, even obviously questionable facilities pass through approval channels with alarming ease. Banking disasters rarely emerge suddenly. They develop gradually through accumulated compromises, tolerated irregularities, suppressed objections, and normalized ethical erosion embedded deeply within institutional cultures that prioritize loyalty over accountability and performance over integrity.
The media also bears responsibility within the ecosystem surrounding bad loans. Financial journalism sometimes glorifies banks primarily through profitability rankings, expansion announcements, and executive lifestyles while insufficiently interrogating asset quality, governance practices, or concentration risks. Public relations narratives often overshadow investigative scrutiny. Shareholders celebrate dividends without examining whether underlying profits rest upon dangerous lending practices likely to explode later. Consequently, warning signs remain ignored until crises erupt dramatically. A healthy financial environment requires courageous journalism capable of questioning institutional contradictions fearlessly. Societies benefit when media examines not only how much banks earn but also how responsibly they deploy the public trust represented by depositors’ resources and economic confidence entrusted into their stewardship.
Technology has improved banking operations enormously, yet technology alone cannot cure ethical decay. Artificial intelligence, automated scoring systems, biometric verification, and digital monitoring tools mean little where human compromise dominates decision making. Sophisticated software cannot protect institutions when influential individuals deliberately override controls for personal interests. Indeed, technological sophistication can sometimes conceal manipulation more effectively by creating illusions of objectivity around fundamentally compromised decisions. Therefore, the future stability of banking depends not merely on innovation but on moral courage. Systems become trustworthy when ethical standards remain stronger than personal greed, political pressure, or institutional ambition. Without integrity, even the most advanced banking architecture eventually collapses under the weight of concealed contradictions and accumulated deception.
The argument that collateral always guarantees repayment also deserves careful examination. Collateral is fundamentally secondary protection rather than primary repayment strategy. The true source of repayment should always be viable business cash flow and sustainable economic productivity. Excessive dependence on collateral can itself encourage complacency because lenders focus more on asset seizure than on evaluating long term business viability. Some institutions approve weak projects simply because attractive collateral exists. This approach is dangerous because distressed asset realization rarely achieves expected values during economic downturns when many borrowers fail simultaneously. Thus, prudent banking requires balanced emphasis on both repayment capacity and enforceable security rather than blind confidence in inflated collateral valuations disconnected from realistic market dynamics.
Another major concern involves regulatory inconsistency. Regulators sometimes react aggressively after crises while remaining passive during the buildup of dangerous exposures. Effective supervision requires continuous vigilance rather than dramatic intervention after damage becomes irreversible. The Central Bank and other supervisory authorities must strengthen early warning systems capable of detecting unhealthy concentration, insider abuse, manipulated restructuring, and deteriorating asset quality before institutions approach collapse. Regulatory credibility depends on proactive independence rather than reactive symbolism. Markets respect regulators who enforce standards consistently regardless of political consequences. When enforcement appears selective or delayed, sophisticated actors quickly learn how to exploit institutional hesitation while ordinary citizens bear eventual economic and social costs arising from preventable supervisory failures.
The moral dimension of bad loans deserves greater attention within public discourse. Banking is not merely a technical industry processing transactions mathematically. It is fundamentally an ethical institution managing collective trust. Depositors sacrifice immediate consumption believing their resources will be protected responsibly. Pensioners entrust lifetime savings into financial systems expecting prudence and integrity. Businesses depend on stable credit intermediation for survival and expansion. Therefore, reckless lending violates more than financial regulations. It betrays societal trust itself. A banker approving irresponsible facilities for hidden incentives is not committing a victimless administrative error. Such behavior can destroy jobs, destabilize families, weaken economies, and undermine confidence essential for national development and social stability across generations.
History provides painful lessons regarding unchecked bad loans. Banking collapses across continents have repeatedly triggered recessions, unemployment crises, currency instability, and widespread social hardship. From Latin America to Asia, Europe to Africa, financial disasters often followed prolonged periods where institutions ignored warning signs while regulators underestimated systemic vulnerability. Toxic assets accumulated quietly behind impressive growth figures until confidence collapsed suddenly. These historical experiences demonstrate that bad loans are never isolated accounting problems. They possess contagious potential capable of infecting entire economies. Consequently, societies cannot afford complacency regarding governance failures within financial institutions. Prevention remains vastly cheaper, safer, and more humane than national recovery after systemic banking crises eventually erupt into public consciousness.
One particularly dangerous practice involves repeated restructuring of obviously distressed facilities merely to avoid recognizing losses publicly. Instead of confronting reality honestly, some institutions extend repayment periods, capitalize unpaid interest, or redesign terms cosmetically while underlying viability remains absent. This creates the illusion of healthy portfolios temporarily but ultimately deepens eventual damage. Delayed recognition does not eliminate risk. It merely postpones accountability while exposures deteriorate further. Transparent recognition of problems allows timely intervention and recovery strategies. Concealment compounds systemic fragility. A banking culture addicted to hiding weakness rather than addressing it honestly gradually becomes vulnerable to sudden confidence crises capable of spreading panic rapidly through financial markets and broader economic systems.
The public often hears bankers describe defaulters as irresponsible individuals unwilling to honor obligations. Certainly, some borrowers act fraudulently and deserve strong sanctions. However, accountability must apply symmetrically. Institutions approving reckless facilities should face consequences equal to those imposed upon delinquent borrowers. Risk managers, executives, valuers, auditors, and directors participating negligently or corruptly in disastrous transactions cannot escape scrutiny merely because borrowers ultimately defaulted. Responsibility within banking is collective rather than unilateral. A failed loan frequently represents institutional failure alongside borrower weakness. Genuine reform therefore requires examining not only who borrowed irresponsibly but also who approved irresponsibly, who supervised negligently, and who ignored warning signs despite professional obligations demanding ethical intervention and prudent oversight.
The concentration of banking wealth and decision making power within narrow elite circles intensifies these problems further. When the same individuals dominate corporate boards, political networks, regulatory influence, and major borrowing entities simultaneously, conflicts of interest become almost unavoidable. Independent oversight weakens because relationships overlap extensively across institutional boundaries. Financial systems thrive best where transparency, competition, and accountability prevent excessive concentration of influence. Diversity of ownership, professional independence, and strong institutional checks create healthier environments than tightly interconnected elite ecosystems vulnerable to mutual protection arrangements. Nations seeking resilient banking systems must therefore address governance structures comprehensively rather than focusing exclusively on technical financial ratios disconnected from deeper institutional realities shaping credit behavior and accountability standards.
The future of banking cannot be sustained merely through higher capital requirements or stricter paperwork alone. Genuine transformation requires rebuilding ethical foundations within financial institutions themselves. Recruitment should prioritize integrity alongside technical competence. Whistleblower protections must become credible and enforceable. Internal dissent should be respected rather than punished. Compensation systems encouraging reckless short term risk taking require redesign. Regulatory bodies need operational independence protected from political manipulation. Above all, society must reject the normalization of financial misconduct disguised beneath sophisticated terminology. A nation that tolerates irresponsible banking eventually mortgages its developmental future because financial systems influence investment, employment, industrial growth, innovation, and economic confidence across every sector of national life and productivity.
Citizens are increasingly questioning why banks aggressively pursue profits during prosperous periods yet seek public sympathy or regulatory rescue when reckless exposures collapse. This asymmetry generates understandable resentment. Gains become privatized while losses threaten socialization through economic instability, inflationary consequences, or taxpayer supported interventions. Such dynamics undermine trust profoundly because they create perceptions that ordinary citizens bear disproportionate burdens arising from elite financial irresponsibility. Sustainable banking legitimacy requires equitable accountability. Institutions benefiting enormously from public trust must equally accept responsibility for protecting that trust prudently. Without moral reciprocity between privilege and responsibility, public frustration toward financial systems will continue intensifying, potentially destabilizing confidence essential for healthy economic and democratic development.
Ultimately, the debate surrounding bad loans is not merely about accounting classifications, provisioning requirements, or technical regulatory frameworks. It concerns truth itself. Are financial institutions genuinely operating according to principles of prudence and transparency, or have sophisticated mechanisms evolved primarily to conceal elite recklessness beneath complicated terminology inaccessible to ordinary citizens? Societies must confront this question courageously because economic stability depends heavily upon institutional trust. Banking systems flourish when citizens believe rules apply fairly, governance remains credible, and accountability transcends political influence. Where deception becomes normalized, confidence deteriorates gradually until crises expose realities previously hidden behind impressive buildings, polished annual reports, and carefully managed corporate narratives celebrating superficial financial success.
As a public policy analyst, I submit that the solution to persistent bank bad loans lies not merely in stricter regulations but in restoring ethical accountability as the soul of financial intermediation. Banks must remember they are custodians of public trust, not private casinos for elite manipulation. The Central Bank must strengthen transparent supervision, enforce personal liability for negligent executives, and eliminate political interference from credit administration. Financial systems become sustainable only where integrity is stronger than influence. Nations that tolerate reckless banking ultimately weaken investment confidence, economic productivity, and social stability. The future of credible banking depends on courageously confronting institutional hypocrisy before it matures into irreversible systemic collapse.