The significance of Tinubu’s Nairobi and Kigali investment-driven trip, Kola Amzat
Since President Tinubu inauguration into office in 2023, he has never left any one in doubt of his intention to launch the country into the midst of industrial nations across the globe and this he’s been pursuing by deploying every available resource to bring in the best of foreign investments to Nigeria.
In realization of this objective, the president has been uncompromising, undeterred, relentless and wily in capitalizing on any available foreign platform, as well as emerging opportunities for the purpose of pleading the Nigerian case.
Fortunately, manifold results have been forthcoming.
The administration has secured over $50 billion in foreign direct investment (FDI) commitments since 2023. These include finalized investments and major corporate pledges across oil & gas, telecoms, agricultures, and port infrastructures sectors.
It’s also instructive to mention the G-20 commitments totaling $14 billion secured at G-20 Summit from companies including Indorama, Airtel and Jinda Steel Industrial expansion.
And not to forget the Tinubu administration’s diplomatic engagements across UK, India, China and Netherlands which have also resulted in broad investment spanning manufacturing, digital technology and renewable energy.
However, the crux of this piece is last week’s president’s diplomatic engagements in Nairobi and Kigali.
The diplomatic engagements in the two key African capitals was totally devoted to re-affirm out in unmistakable terms Nigeria position to the global community, enumerating African challenges with the entire globe, as well as laid bare unto the international community the expectations of African, and in the same vein, challenged African leaders to have a rethink, with respect to turning the tide of African continent.
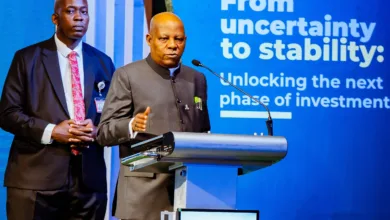
In Nairobi, the president, amongst other African leaders, engaged in intense meetings with world financial institutions, development partners, as well as global private investors.
For Nigeria, the take home from that engagement is the IFC declaration of a plan to send an investment mission to explore the possibility of scalable opportunity in livestock, housing, energy and housing.
Additionally, APM terminals affirmed that commitment for fresh $600 million in the nation’s maritime sector.
While in Nairobi, capital city of Kenya, the president audaciously affirmed to the gatherings of eminent personalities across the globe, including UN Secretary General and France President, Emman Macron that African continent was not demanding for charity and that, what the continent is pleading for from the rest of the world is equity and fairness.
The president reiterated that the current global financial architecture was already intentionally skewed against African entrepreneurial development.
The president affirmed that Africa is already entangled in challenges of exporting raw materials cheaply and tragically importing manufactured products at very astronomical prices owing to African countries being consistently denied affordable capital.
Tinubu vehemently questioned the excessive dependence of African trades on foreign currencies, and to solve the problem, Nigerian president suggested vibrant and robust regional financial, possibly African commodity exchange platform, as well as Credit Rating that would have African root and would engage forthwith in providing genuine and correct rating for the countries and business entrepreneurs in the continent.
Meanwhile, In Kigali, the president was very blunt to African leaders who attended. He challenged the leadership of the continent to halt forthwith the archaic habit of waiting for the countries across the globe to start developing the continent, admonishing them to take the bull by the horns by taking the future of the continent firmly in their hands.
Tinubu affirmed to African leaders that the continent has all the resources needed to blossom and flourish and that, the challenges of the continent remains lack of robust policy, effective coordination and economic integration to drive the African cause.
The Nigerian president declared to African leaders that the country had attracted close to $20 billion in foreign direct investment in 2026 alone owing to various reforms of the administration.
And, while with Nicholas Norbrook, the president defended various reforms of his administration-fuel subsidy removal, exchange rate, tax and petroleum reforms, as well as affirming the justifiable reasons for embarking on the reforms.
It’s important to note that the president deployed Nairobi and Kigali engagement platforms projecting the strategic global view that sees Nigeria not as on-looker in the global affairs, but rather, as a country fully ready to speak audaciously, pursue reforms in an unprecedented manner, as well as pushing for a new order in Africa with respect to greater and economic self-sufficient.
The three engagements of the president in Nairobi and Kigali were eventful, informative and apt enough to plead Nigeria’s case to the global community.
Kola AMZAT (FCA, FCIB, ACS, MBA),
09077509348, [email protected]