Pat Utomi: Time to take a back seat — by Temitope Ajayi
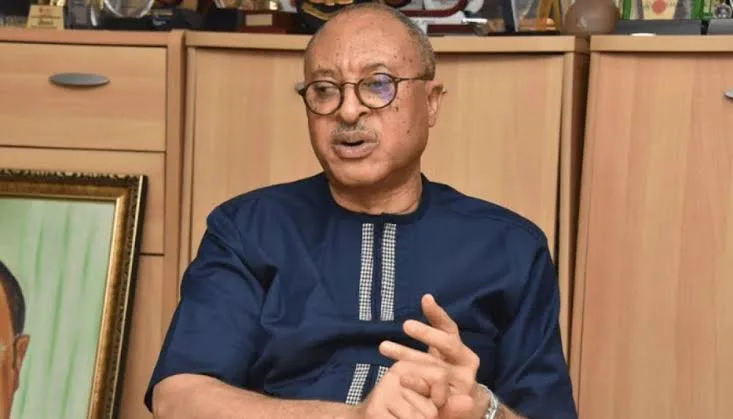
Since bursting into national consciousness, Professor Patrick Utomi has convinced himself that he is the Nigerian equivalent of Albert Einstein, Adam Smith and John Maynard Keynes rolled into one.
For decades, as a public intellectual/commentator on national affairs and economic matters, Utomi has consistently shared his views on the world and on how Nigeria’s political economy should be constructed. Like Peter Obi, his newfound comrade-in-arms, Utomi copiously cites examples from South Korea, Malaysia, Singapore, Indonesia and Chile, among others. While there is no doubt about the quantum of economic theories Utomi has memorised, there is always a limit to book knowledge when the realities of the real world show up.
In the furnace of the real world, Utomi has been tried, tested and allowed to demonstrate the applicability and practicality of his ideas. While he has had the opportunity at many fora to defend his own record, the verdict remains that he did not cover himself in glory as Managing Director/Chief Executive of the defunct Volkswagen of Nigeria and as the Vice Chairman of BankPHB of equally blessed memory.
From the sordid details revealed in court after forensic investigators visited, Utomi essentially presided over a bank where depositors’ funds were converted into private pockets in the most primitive way. Alas, the enterprises that would have been a showpiece or foretaste of what Utomi is capable of doing at a higher level of public leadership went down under his “brilliant” watch.
At BankPHB, there was also a massive shareholder value erosion and insider abuse. Francis Atuche, the bank’s Chief Executive, is serving a jail term for the mismanagement of a bank in which Utomi served on its Board of Directors. Were Utomi really capable of any sense of propriety, he ought to be in self-seclusion over the unravelling of BankPHB and not continue his often annoying career of sophistry and peddling of untested economic doctrines.
The other side of Utomi was also exposed when Senator Ibikunle Amosun claimed an NGO controlled by the self-styled political economist had offered him an unsolicited award, ostensibly to influence him to approve an unfair consideration in a disputed property case before him while he was Ogun State Governor. So much for a moral crusader!
Overall, there is a pattern to Utomi’s intellectual arrogance. Every four years, he comes out to mount a moral high horse on who should lead Nigeria. He touts himself as a political strategist with an uncanny ability to cobble victory at the polls for whoever he backs. Yet, time and again, he has failed. But rather than accept loss with humility and introspect as an intellectual should do, he will rather raise a storm. That was what he did in 2023, using his social media platform to mislead the gullible at a critical time, proclaiming his candidate’s victory before the election results were announced.
As another election season is upon us, Utomi has again taken to shooting from the hip, even when facts and logic are not on his side, attempting to discredit President Bola Tinubu’s leadership of Nigeria and to describe his reform agenda in unflattering terms.
Feeling over the moon immediately after the convention of his own faction of ADC in Abuja, Utomi was on television, pouring invectives on President Tinubu and the governing APC. He also took out a ThisDay newspaper back page where he labelled the ongoing economic reform programme as “ridiculous”, dismissing it as a “Ponzi scheme.” Here is a man who, out of political convenience, is attacking the same free-market economic offerings and prescriptions he built his public acclaim on.
For far too long, Utomi and those of his ilk have held themselves up as the moral arc of society and their economic prescriptions as canon.
Once any administration refuses to lean on them and their personal economic and political interests do not find immediate accommodation, personal frustration is then packaged and presented as national outrage. Yet, when he was finding favour in Asiwaju’s eyes, Utomi used to frequent his Bourdillon home, extolling his generous host to the high heavens as “visionary”. In fact, a viral video shows Utomi dancing ecstatically to “Sakara” music in a casual shirt and trousers behind Asiwaju Tinubu at his Bourdillon residence, moments after the APC was declared the winner of the 2015 polls.
He was among those who courted Tinubu to advance their own political ascendancy. If Tinubu had supported and funded his ambition to be Delta State governor in 2019, as he wanted, Utomi would be dancing to a different drumbeat today. While for decades, Utomi has told us many things that are wrong with Nigeria, even if he has failed at the micro level to demonstrate how to put things right, it is now time for him to take a back seat from his selective outrage.
–Ajayi is Senior Special Assistant to President Tinubu on Media and Publicity

Rejoinder: Pat Utomi, Time to Take a Back Seat
The article titled “Pat Utomi: Time to take a back seat”, published on April 17, 2026 in TheCable and authored by Temitope Ajayi, purports to critique the public economic commentary of Pat Utomi. However, rather than engaging with the substance of Utomi’s arguments on macroeconomic instability, institutional fragility, and policy sequencing, the piece relies heavily on personality framing and retrospective association. In effect, it substitutes empirical reasoning with narrative convenience.
Utomi’s core arguments sit within established frameworks of political economy: the relationship between macroeconomic stability and industrial performance, the role of institutional credibility in investment outcomes, and the importance of reform sequencing in developing economies. These are measurable constructs. Inflation trajectories, exchange rate volatility, industrial capacity utilization, and banking sector non-performing loan ratios are all observable indicators that shape outcomes. A rigorous rejoinder would engage these variables directly. The article does not.
Instead, it constructs causality through participation: because Utomi held leadership roles in Volkswagen of Nigeria and served in governance at Bank PHB, he is retrospectively positioned as a causal agent of their outcomes. This reflects a methodological error in causal inference known as post hoc ergo propter hoc, where temporal sequence is mistaken for causation. In empirical analysis, especially within economics and corporate governance, sequence alone is insufficient without controlling for structural variables.
Volkswagen of Nigeria operated within an import substitution industrialization regime whose performance was structurally dependent on macroeconomic stability and trade protection. Empirical data from Central Bank of Nigeria industrial reports and World Bank enterprise surveys show that from the mid-1980s onward, Nigeria experienced sustained exchange rate depreciation, rising input costs, and declining manufacturing capacity utilization across sectors. These are systemic shocks that altered the entire production frontier of domestic industry.
From a methodological standpoint, this is a textbook case of binding constraint dominance. In constrained optimization models in economics, when macro constraints become binding, marginal firm-level decisions have diminishing explanatory power over outcomes. In simpler terms, when the operating environment collapses, managerial skill cannot restore equilibrium. Volkswagen of Nigeria’s decline therefore aligns more strongly with macroeconomic restructuring than with individual managerial agency.
The same logic applies to Bank PHB. The 2009 Nigerian banking crisis was not an isolated institutional failure but a correlated system-wide breakdown. Following the 2004 consolidation reforms, banks expanded credit exposure aggressively into capital markets and high-risk lending portfolios. Regulatory oversight, later acknowledged as insufficient by the Central Bank of Nigeria under Sanusi Lamido Sanusi, failed to adequately constrain systemic risk accumulation.
By the time distress became visible, non-performing loan ratios had reached crisis thresholds across multiple institutions, not just Bank PHB. In financial economics, this is classified as systemic risk crystallization, where correlated exposures across firms lead to simultaneous failure. In such contexts, isolating one board member or chairman as a causal determinant violates basic principles of risk attribution.
Importantly, Utomi’s role as chairman occurred during crisis resolution rather than risk accumulation, following earlier leadership under Kola Abiola. Corporate governance theory distinguishes between risk origination phases and crisis management phases. Causal responsibility is weighted toward the former. Conflating these phases reflects a failure to apply temporal causality, a core requirement in institutional analysis.
Beyond empirical issues, the article exhibits two major cognitive biases that weaken its analytical credibility.
The first is confirmation bias, which occurs when evidence is selectively interpreted to reinforce a pre-existing conclusion while ignoring disconfirming data. The article foregrounds Utomi’s institutional affiliations but omits macroeconomic indicators, sector-wide banking data, and comparative historical evidence that contradict the implied narrative. For example, the simultaneous decline of multiple manufacturing firms and the systemic nature of the 2009 banking crisis are well documented. Their exclusion is not neutral; it is selective framing.
The second is fundamental attribution error, which involves overemphasizing individual agency while underweighting structural constraints. The article attributes complex institutional outcomes to personal decisions while discounting macroeconomic shocks, regulatory failures, and infrastructural deficiencies. This bias is particularly common in politically charged environments where visible individuals are easier to assign responsibility to than abstract systems. However, in empirical economics, visibility is not causality.
These biases collectively produce a distorted explanatory model in which structural failure is personalized and system-level causation is minimized. The result is not analysis but attribution substitution, where institutional explanations are replaced with character-based reasoning.
It is also methodologically inconsistent to critique Utomi’s economic worldview while relying on a framework that ignores basic principles of comparative political economy. Cross-country analysis, including references to economies such as South Korea, Malaysia, or Chile, is not rhetorical decoration but standard empirical methodology used to evaluate institutional performance under varying policy regimes. Dismissing such comparisons as “book knowledge” signals a rejection of established empirical practice rather than a refutation of it.
Arturo Bris, in The Right Place: How National Competitiveness Makes or Breaks Companies, provides a direct empirical counterpoint. His research demonstrates that firm outcomes are systematically shaped by national competitiveness indicators including regulatory quality, infrastructure adequacy, macroeconomic stability, and institutional strength. Across datasets, firms operating in low-competitiveness environments exhibit higher failure rates independent of managerial quality. Nigeria’s historical performance on these indicators during the relevant periods consistently explains industrial decline and banking fragility more effectively than individual-level attribution.
What is missing in the article, therefore, is not rhetorical confidence but methodological rigor. Economic analysis requires identification of causal variables, control for confounders, and attention to temporal sequencing. Business history requires separation between firm-level decisions and systemic constraints. Political economy requires recognition that institutions shape incentives long before individuals act within them. None of these analytical requirements are met in the rejoinder.
Ultimately, the weakness of the argument lies not in disagreement with Utomi, but in its inability to demonstrate causality beyond assertion. It confuses participation with responsibility, correlation with causation, and narrative coherence with empirical validity.
The real question is not whether Pat Utomi should “take a back seat.” The real question is whether public economic commentary in Nigeria can meet the basic standards of evidence-based reasoning. On the basis of the available analysis, this particular rejoinder does not.