Nigeria’s aspiration to build a $1trn economy requires banks capable of mobilising, allocating capital, says CBN
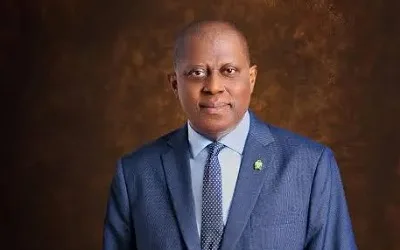
The Deputy Governor, Corporate Services, Central Bank of Nigeria (CBN), Dr. Muhammad Abdullahi on Tuesday said Nigeria’s aspiration to build a $1trillion economy by 2030 requires banks capable of mobilising and allocating capital on a much larger scale.
Abdullahi , giving his keynote address at the 38th Seminar for Finance Correspondents and Business Editors annual conference in Lagos stated that stronger capital buffers is expected to enable banks to finance long-term infrastructure, support industrial expansion, facilitate international trade and compete more effectively in regional and global markets.
The theme for the 38th Seminar is: “Towards a Robust and Resilient Financial System in the Post-Banking Sector Recapitalisation Era”.
According to him, banks also need to provide greater capacity to absorb losses during economic stress and sustain investment in innovation and digital transformation.
Speaking further he said, “The environment in which these banks operate is increasingly interconnected.
“Geopolitical uncertainty, climate-related risks, cyber threats and rapid technological change can transmit shocks across borders through financial, trade and technology channels, affecting capital flows, exchange rates and external buffers.
“Resilience therefore requires institutions to anticipate emerging risks, absorb shocks, adapt and recover. The lessons of past financial crises underline the value of adequate capital, but also the need to prepare for risks that may take unfamiliar forms.
“Capital, however, is a starting point. Boards and management must maintain sound controls, recognise risks early and lend on the strength of viable projects.
“Sound corporate governance must underpin that work. Boards and management teams must demonstrate integrity, accountability and transparency, strengthen internal controls and guard against excessive risk-taking.
“Their decisions must protect the interests of depositors, investors and other stakeholders. Risk management must extend beyond credit risk to market, liquidity and operational risks, as well as cybersecurity, third-party dependencies and climate-related financial risks. Banks need frameworks that identify these exposures early and allow management to respond before they threaten the institution’s resilience.”
Abdullahi pleased that the apex banking regulating body would continue to pay close attention to governance, asset quality, liquidity and large exposures.
“We will also expect banks to protect customer data, maintain reliable payment services and recover quickly from disruptions. A stronger balance sheet must be matched by stronger management of risk.
“As more financial services move to digital channels, banks must invest continuously in cybersecurity, data protection, disaster recovery and business continuity. Innovation brings opportunities, but public trust depends on customers being able to transact securely and access their funds reliably, including when systems come under pressure.
“Our supervisory approach will continue to emphasise risk-based supervision, macroprudential surveillance and enhanced stress testing. Financial sector coordination, consumer protection, fintech regulation and support for responsible innovation will remain important, alongside crisis preparedness and resolution planning.
“As the Governor has consistently emphasised, preserving monetary and financial stability requires continued vigilance. We must remain forward-looking, data-driven and responsive to developments at home and abroad,”he said.
According to him, the wider economy should see the benefit over time. Agriculture, manufacturing, services and infrastructure need finance suited to their cash flows and investment horizons.
“Smaller firms and households need dependable payments, appropriate products and fair treatment. We should assess recapitalisation by the quality of banking services and productive lending it supports, as well as by the amount of capital raised.
That benefit must reach rural communities, women and young entrepreneurs, as well as customers already served by the formal financial system. Consumer protection and financial inclusion are integral to resilience: a system that people can access, understand and trust is better able to support lasting growth. Stronger bank balance sheets should translate into wider access and better service.
He stated that financial correspondents and business editors are important intermediaries between policymakers, financial institutions, investors and the public.
“Accurate and objective reporting strengthens market transparency, supports investor education and enables informed public debate. In an environment where information travels rapidly across platforms, fact-based reporting, analytical depth and constructive engagement are essential to sustaining confidence,” he added.