JUST IN: KPMG misunderstood key provisions of new tax laws, says Presidency
By Kunle Sanni –
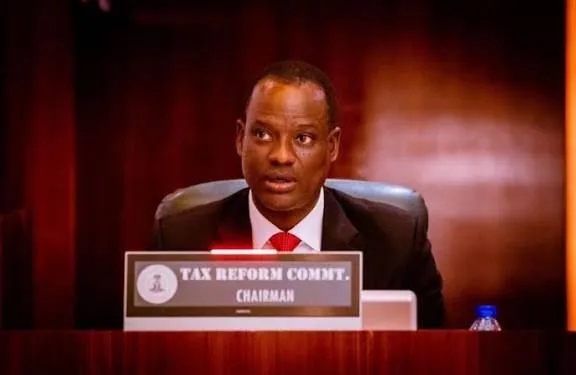
The Presidential Fiscal Policy and Tax Reforms Committee has refuted concerns raised by global advisory firm Klynveld Peat Marwick Goerdeler (KPMG) regarding Nigeria’s newly enacted tax regime, dismissing many of the criticisms as misunderstandings of the law’s intent and structure.
In a statement released on Saturday, the committee said it is open to feedback that enhances implementation of the reforms, acknowledging that some issues highlighted by KPMG, particularly around operational risks and editorial corrections, were valid. However, the committee said much of KPMG’s commentary misunderstood both the purpose and design of the reforms, conflating policy choices with errors.
KPMG, through its regular tax newsletters and advisory briefs, faulted Nigeria’s new tax law, highlighting inconsistencies, gaps and omissions in the document. KPMG stated that “there are certain errors, inconsistencies, gaps, omissions and lacunae in the new tax laws that need to be urgently reconsidered to ensure the attainment of the stated objectives.” The firm highlighted 31 loopholes bordering on the identified shortcomings in the new tax law and suggested modifications.
In its response, the committee disputed KPMG’s description of many provisions as “errors,” “gaps” or “omissions,” arguing instead that most were either mistaken interpretations by the firm, matters KPMG did not fully contextualise within broader reform goals, or preferences for alternative outcomes.
The committee suggested KPMG’s critique may have been more effective if the firm had engaged with authorities directly — similar to how other professional services firms have participated in consultations — rather than framing disagreements as legislative flaws.
This distinction matters because global firms like KPMG — which regularly issue technical tax insights meant to guide multinational clients — differentiate between policy criticism and drafting critique.
Addressing KPMG’s concern that tax changes would prompt capital flight from Nigeria’s stock market, the government clarified that the chargeable gains tax is not a flat 30% rate. Instead, it ranges from 0% up to 30%, with most investors — estimated at 99% — qualifying for exemptions either unconditionally or through reinvestment.
Responding to concerns that provisions taxing indirect transfers of shares could harm competitiveness, the committee defended the measure as part of Nigeria’s compliance with Base Erosion and Profit Shifting (BEPS) standards — a global framework developed by the OECD to prevent tax avoidance by multinational firms.