The rise and fall of Ibeto cement: lessons Nigeria must not ignore, by Chioma Ahaghaotu
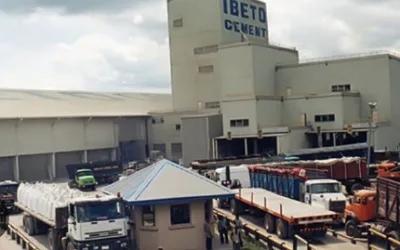
Ibeto Cement was once a dominant name in Nigeria’s cement market. For years, it played a critical role in supplying one of the country’s most essential construction materials, helping bridge gaps in a market that was once heavily dependent on imports. At its peak, Ibeto was a major importer and bagger of cement, with a footprint large enough to influence prices, supply, and availability.
Today, however, the company barely registers in the industry. Its decline was not sudden, and it was not caused by a single event or hidden hand. It was the result of a convergence of policy shifts, structural weaknesses, capital constraints, intense competition, and strategic miscalculations, all unfolding within a rapidly changing industrial environment.
The turning point came with Nigeria’s backward integration policy.
In an effort to reduce import dependency, conserve foreign exchange, and drive industrialization, the government required cement importers to transition into full local manufacturing.
On paper, the policy made sense. In practice, it fundamentally changed the rules of the game.
Ibeto’s business model was built primarily on importing bulk cement and bagging it locally.
While this created jobs and added value, it no longer met the government’s new definition of industrial contribution.
Once import licenses and bagging privileges were withdrawn from companies that failed to establish manufacturing plants, Ibeto lost the core of its revenue almost overnight.
This was not merely regulation; it was a forced transformation, and companies that could not pivot fast enough were structurally edged out.
As enforcement tightened, competition became ruthless.
Legal and regulatory battles emerged, including disputes with larger players over import quotas and compliance.
This was not unusual.
In sectors like cement, competition is fought not only in the marketplace but also through policy interpretation, regulatory alignment, and litigation.
Cement is a strategic commodity, and the state is deeply embedded in how the market functions.
During this period, fully integrated producers moved aggressively. Massive plants were built, limestone mining rights were secured, captive power systems installed, and supply chains vertically integrated.
Once these companies aligned fully with government policy, they gained decisive cost and regulatory advantages.
Ibeto, still without a functioning manufacturing base, found itself increasingly boxed out as the market consolidated.
It is important to note that Ibeto did attempt to transition.
Over the years, the company announced multiple plans to enter cement manufacturing, including efforts to revive dormant plants and attract foreign capital.
In 2018, reports even emerged of an $850 million financing agreement with international partners to establish local production.
Yet, as is common with large-scale industrial projects in Nigeria, execution proved far more difficult than announcement.
Cement manufacturing is brutally capital-intensive, that is why many do not venture into it.
It requires massive upfront investment, reliable power, access to limestone reserves, efficient logistics, and the patience to wait years before profitability.
Without deep balance sheets or sustained policy-backed financing, the transition from importer to manufacturer becomes extraordinarily difficult.
By the time Ibeto’s manufacturing ambitions gained traction, the policy window had narrowed and the market had already consolidated around fully integrated producers.
At the same time, Nigeria’s cement market shifted toward oversupply as large producers ramped up capacity. While this improved availability, it intensified competition and compressed margins.
Persistent structural problems, high energy costs, unreliable power supply, poor transport infrastructure, and logistical inefficiencies, further punished companies without scale.
Large integrated companies could absorb or internalize these costs. Smaller or transitioning players could not.
Ibeto, without its own production base, lacked the resilience to compete sustainably under these conditions.
There are those who argue that Ibeto’s fall was primarily driven by tribal bias, that the company was deliberately suppressed because its founder is Igbo.
This argument is emotionally understandable in a country where ethnicity often frames political debate, but it does not hold up under serious industrial analysis.
Nigeria’s cement policy did not target individuals or ethnic groups; it targeted business models.
Backward integration was the dividing line.
Companies that complied survived and expanded.
Those that did not were squeezed out, regardless of ownership.
The success of today’s dominant players is often mistaken for ethnic favoritism, but this confuses outcome with intent.
Their advantage came from early and aggressive compliance with policy, massive capital deployment, vertical integration, and strategic alignment with regulators.
If ethnicity were the determining factor, compliance would not have mattered, non-integrated firms would have been protected, and integrated firms from outside “favored” groups would have been excluded.
None of this happened.
Ibeto’s decline was structural, not tribal, and misdiagnosing it as ethnic exclusion risks learning the wrong lessons.
That said, the government is not blameless.
While backward integration was well-intentioned, its implementation was often abrupt and unforgiving.
Clearer transition timelines, phased compliance, structured financing, and consistent policy signals could have allowed more indigenous firms to scale successfully.
Industrial policy should not merely reward those who already have deep capital; it should create credible pathways for capable players to grow.
Too often, the state acted as a gatekeeper rather than an enabler.
For future industrialists, the lessons are hard but clear.
In regulated, capital-intensive sectors, policy alignment is not optional. Vision without capital is fragile. Lobbying, coalition-building, and collective action matter.
Fragmented players are easily overwhelmed, while coordinated industries can influence regulation and stabilize markets.
Successful industrialists do not only build factories; they build relationships, anticipate policy shifts, and move early.
The demise of Ibeto Cement is not a story of sabotage or sentiment.
It is a case study in how industrial transitions reward preparedness and punish delay.
Vision alone is not enough.
In Nigeria’s industrial landscape, survival is determined by execution, capital, compliance, coordination, and strategic foresight.
If we fail to absorb these lessons, we will continue to produce cautionary tales instead of enduring industrial champions.
By Chioma Amaryllis Ahaghotu